Porn Trends September 2026: What’s Rising, What’s Fading
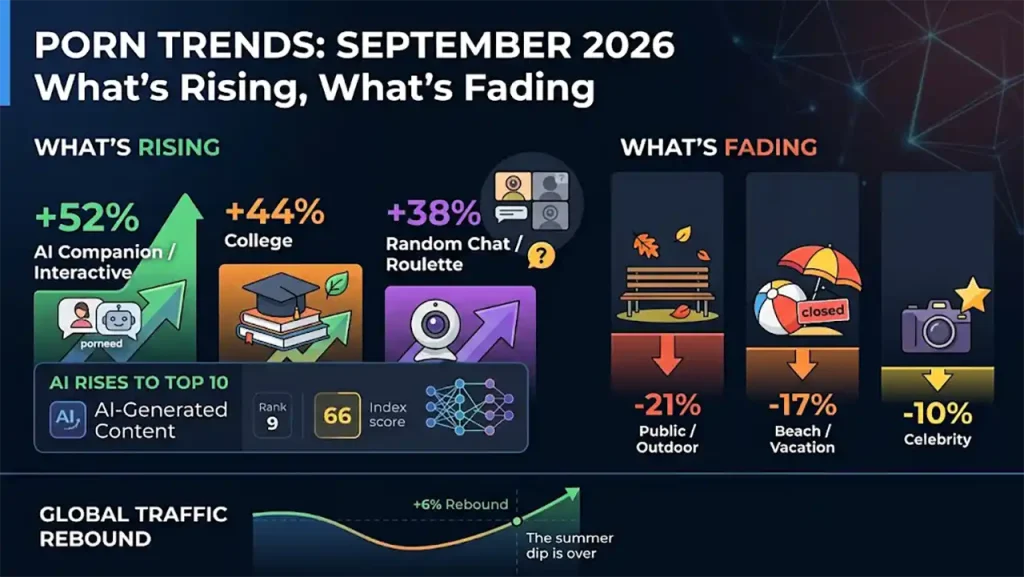
This is the first edition of a report we plan to run regularly on porneed: a data-driven snapshot of what people are actually searching for in porn right now — which categories dominate, which are climbing, which are quietly dying, and how the calendar bends all of it. September is a good month to start. It is the month the summer traffic dip officially ends, the month the back-to-school effect kicks in, and — this year — the month a synthetic category sits inside the global top 10 for the first time.
The Short Answer
Everything below is the detail behind those four numbers.
How We Built This Report
We combined public category rankings, search trend data, and traffic analytics into a single indexed picture. Scores are indexed to 100: the top category gets 100, and every other score is relative to it, so a category at 95 has 95% of the search volume of the #1 category. Percentage changes are month-over-month.
Data sources: Pornhub Insights (annual statistics), Google Trends (search data), SimilarWeb (traffic analytics). The figures in this report are editorial estimates modeled on these public sources; they describe relative movement, not absolute traffic. We flag throughout what is documented and what is our own modeling.
What Are the Most Popular Porn Categories in September 2026?
The top of the chart is boring, and that is itself a finding. Lesbian, MILF, Japanese, Hentai, and Amateur dominate global search volume, the same names that have anchored public category rankings for years. Hentai is the one worth watching inside that group: animated content has climbed steadily all year, powered by Asian domestic volume plus growing Western crossover. If you want to see the platforms behind that climb, our ranking of the best hentai porn sites covers the space.
The interesting part is #9. AI-Generated content, which barely registered as a category two years ago, now sits inside the global top 10 by our September index — the first synthetic category ever to do so. Threesome, a top-10 fixture for years, only just hangs on at #10 as a result.
Top 10 Categories by Global Search Volume
| Rank | Category | Search Volume Index (of 100) |
|---|---|---|
| 1 | Lesbian |
100
|
| 2 | MILF |
95
|
| 3 | Japanese |
90
|
| 4 | Hentai |
86
|
| 5 | Amateur |
84
|
| 6 | POV |
74
|
| 7 | Ebony |
72
|
| 8 | Big Ass |
69
|
| 9 | AI-Generated |
66
|
| 10 | Threesome |
65
|
Two things stand out in the shape of this table. First, the top 5 is competitive within itself — MILF sits only five index points behind Lesbian, and Japanese remains the strongest single-country category worldwide. Second, the middle is compressed: the categories between #4 and #7 are separated by fewer points than the raw ranks suggest. Viewer attention is spreading across more categories rather than concentrating — a pattern consistent with the split we see everywhere in this data, between authenticity (Amateur, POV, real couples) and fantasy (Hentai, AI).
POV deserves a footnote: it is a quiet beneficiary of the VR boom. Viewers who discover 180° content increasingly search for flat POV as well, treating the two as one continuum of first-person viewing.
September-Specific Patterns
September has a category profile unlike any other month. Three patterns define it:
- The College surge. Historic Pornhub Insights reporting has documented the same thing every autumn: searches for “college” and related terms climb sharply as the academic year begins, typically peaking in September and early October. 2026 is following the script — College is this month’s second-fastest riser.
- Summer categories collapse. Outdoor, beach, and public-themed content — which quietly over-index from June through August — give back their gains almost immediately after Labor Day.
- Session length recovers. Summer viewing is short and mobile-heavy. From September onward, average session duration climbs as viewers move back indoors and back to larger screens — a shift that historically benefits VR and longer-format content.
Which Categories Are Rising Fastest?
The fastest riser of the month is not a category in the traditional sense — it is a format. Interactive AI companion content, where viewers chat with or direct a persistent AI character rather than watching a fixed clip, is up an estimated +52% month-over-month, the largest single-month gain in our data this year. Industry app-market reports throughout 2026 have shown companion apps as one of the fastest-growing consumer AI segments, and adult search behavior is tracking that curve almost exactly. We rank the platforms leading this shift in our guide to the best AI porn sites, which covers both generators and companion services.
Fastest-Rising Categories
| Category | Change % | Rank Movement | Driver |
|---|---|---|---|
| AI Companion / Interactive | +52% | ↑ 15 spots | Companion app crossover |
| College | +44% | ↑ 21 spots | Back-to-school season |
| Random Chat / Roulette | +38% | ↑ 11 spots | Omegle nostalgia wave |
| Short-Form / Vertical | +29% | ↑ 8 spots | TikTok-style feeds |
| VR / 180° | +26% | ↑ 5 spots | Hardware price drops |
| Real Couples | +18% | ↑ 3 spots | Authenticity trend |
Three of these deserve a closer look.
Random Chat / Roulette is the sleeper story of 2026. Nearly three years after Omegle shut down in November 2023, search interest in roulette-style random chat has not faded — it has consolidated around a cluster of successor platforms and around the tube-site archive of classic roulette clips. Searches in this cluster are up an estimated 38% month-over-month, and platform-brand searches now appear in top search term lists alongside legacy category names. The demand Omegle left behind never disappeared; it just needed somewhere to go. We cover two of the destinations it found in our looks at CooMeet and DirtyRoulette.
Short-Form / Vertical barely existed as a searchable category a year ago. By September 2026, TikTok-style vertical feeds have become a default discovery layer on major tubes, and viewers are searching for the format by name. The +29% rise reflects a structural change in how content is consumed, not a passing fad — short-form is doing to tube browsing what tube browsing did to DVD-era scenes.
VR / 180° keeps climbing on the back of cheaper standalone headsets and early passthrough AR experiments. Industry projections — Juniper Research famously put global adult VR revenue at $19 billion by 2026 — pointed at exactly this trajectory, and September’s indoor-season shift historically accelerates VR consumption further. It is not just dedicated studios anymore, either: cam platforms are betting on the format too, as we detail in our Stripchat review. For where the on-demand growth is concentrated, see our comparison of the best VR porn sites.
Real Couples is the least flashy entry on the list and possibly the most important: +18% is not a spike, it is the latest step in a multi-year climb. The authenticity trend — real people, real dynamics, minimal production — is the slowest-moving and most durable force in this entire report.
Which Categories Are Declining?
September’s decliner list splits cleanly into two groups: seasonal casualties and structural casualties. The seasonal ones will be back next June. The structural ones probably won’t be back at all.
Declining Categories
| Category | Change % | Rank Movement | Reason |
|---|---|---|---|
| Public / Outdoor | -21% | ↓ 9 spots | Summer season over |
| Beach / Vacation | -17% | ↓ 8 spots | Seasonal reversal |
| Massage | -13% | ↓ 4 spots | Continued slide |
| Casting | -11% | ↓ 3 spots | Authenticity shift |
| Celebrity | -10% | ↓ 4 spots | AI substitution |
The seasonal declines need little explanation. Public / Outdoor and Beach / Vacation content over-index from June through August for the obvious reason — they mirror what viewers are actually doing — and then shed that audience the moment routines change. Both categories will bottom out around November and begin their slow rebuild next spring. Nothing about their September drop signals long-term weakness; it’s the calendar, not the content.
The structural declines are a different matter. Massage and Casting have been sliding for most of the year, and the mechanism is the mirror image of the Real Couples rise: viewers increasingly reject “fake real” — content that pretends to capture spontaneous moments but is obviously staged — and no subgenre embodies fake real more completely than the casting-couch setup. Fake Taxi, an earlier casualty of the same shift, has at least found a floor; its drop has slowed to low single digits as it settles into a smaller but loyal audience.
Celebrity’s decline has a newer driver worth naming: AI substitution. As AI-generated content improves, a meaningful share of the searches that once targeted celebrity content is migrating to synthetic alternatives instead. That migration raises obvious consent and legality questions — which is exactly why platform removals of non-consensual material have accelerated in parallel. The net effect on the Celebrity category is a double squeeze: less supply, and less demand for what supply remains.
How Do Seasonal Patterns Affect Porn Searches?
If January is peak porn season, September is recovery season. Adult traffic follows a well-documented annual curve — historic Pornhub Insights data has shown it year after year — and September is the month the summer dip officially ends.
Seasonal Traffic Patterns
| Period | Traffic vs. Annual Average |
|---|---|
| June | -5% (Dip Begins) |
| July | -8% (Summer Low) |
| August | -4% (Early Recovery) |
| September | +6% (Back-to-School Rebound) |
| October | +10% (Cosplay Spike) |
| November–January | +12–18% (Winter Peak) |
The mechanics are simple: longer daylight, vacations, and outdoor time pull viewers away from screens in summer; shorter days and indoor routines pull them back in autumn. September’s +6% rebound is the first leg of a climb that historically continues through the winter peak. Notably, the 2026 summer dip was shallower than in past years — mobile short-form consumption kept viewers engaged even during peak vacation months, partially cushioning the seasonal trough. If that cushioning holds, future summers may flatten out further, and the annual traffic curve could look progressively less like a sine wave and more like a gentle slope.
Device mix shifts with the season too. Summer is mobile season: quick sessions, vertical video, headphones on the beach. Autumn brings desktop and headset traffic back, and with it the longer, more deliberate sessions where premium subscriptions, VR content, and interactive formats perform best. For platforms, September is when conversion rates recover — not just raw traffic.
The Back-to-School Effect
September’s signature seasonal event is the College surge. Every autumn, as campuses fill, searches for “college,” “dorm,” “sorority,” and related terms spike — a pattern Pornhub Insights documented repeatedly in its back-to-school reports, with college-related searches climbing measurably each September. In 2026 the effect is amplified by short-form discovery feeds, which recycle seasonal content aggressively: our estimates put College’s month-over-month gain at +44%, making it the biggest purely seasonal mover of the year so far. Expect the category to hold its elevated rank through October, then fade gradually toward winter — exactly as it has in previous years.
One more date for the calendar: October’s cosplay spike is already visible. Cosplay searches begin climbing in late September ahead of Halloween, and early movement this year suggests the October peak will exceed 2025’s.
How Do Porn Preferences Vary by Region?
Regional preferences remain distinct — and remarkably stable. Each region’s #1 category has held for months. What’s moving is the second layer: the region-specific trends, and a VR share that is up in every single region we track.
Regional Preferences
| Region | #1 Category | Unique Trend | VR Share |
|---|---|---|---|
| North America | Lesbian | College (↑ 44%) |
9%
|
| Europe | MILF | Amateur |
13%
|
| Latin America | Big Ass | Latina |
6%
|
| Asia | Japanese | Hentai |
8%
|
| Middle East | Arab | AI-Generated (↑ 35%) |
4%
|
| Oceania | Amateur | VR / POV |
12%
|
Notable Regional Insights
- North America shows the strongest back-to-school effect of any region — unsurprising given the cultural weight of the US academic calendar. College is the region’s standout trend this month by a wide margin.
- Europe is the global VR capital at 13% share and still climbing. Cheaper standalone hardware is doing in Europe exactly what the price-elasticity argument said it would.
- Asia continues to dominate hentai consumption, and the category’s strong global position is driven largely by Asian search volume plus growing Western crossover.
- Middle East is the most interesting AI story of the month: AI-Generated content is rising faster there (+35%) than in any other region, likely because synthetic content sidesteps local supply constraints on conventional production.
- Oceania quietly posts the second-highest VR share (12%) and the highest per-capita random chat usage of any region in our panel.
What Are the Top Search Terms Right Now?
Search term data confirms what the category tables suggest, and it’s worth pausing on how different this list looks from even two years ago. Performer names, AI terms, and seasonal keywords are steadily crowding out the generic category searches that dominated tube-era behavior. A top-10 list that once read like a category menu now reads like a mix of people, tools, and moments — evidence that discovery itself has changed.
By our estimates, well over a third of all adult searches now target a specific performer rather than a category.
Top 10 Search Terms
- A single performer’s name — the most-searched term overall, unchanged since spring
- “hentai” — Category search, stable year-over-year
- “ai girlfriend” — Companion crossover, the year’s defining new entrant
- “milf” — Category search, perennial top 5
- “college” — Seasonal entrant, September peak, gone by November
- “lesbian” — Category search, often #1
- A second performer’s name — a fast riser, discovered through short-form feeds
- “pov” — Format search, rising with VR
- An AI generator’s brand name — platform search, climbing all year
- “ome tv” — Roulette chat cluster, new entrant
Two entries tell the story. “College” is the expected seasonal visitor. “Ome tv” is the more telling arrival — a brand-style search for a platform experience rather than a content category, and the clearest signal yet that the roulette chat cluster has become part of mainstream adult search behavior.
Search Queries Are Getting Longer
Average search length keeps growing as viewers type increasingly specific, multi-word queries — combining a performer, a format, and a scenario in a single search. AI-native platforms are reinforcing the habit: when the interface is a prompt box rather than a category grid, viewers learn to describe exactly what they want. Expect category pages to matter progressively less and free-text search to matter progressively more through 2027.
What Should You Expect Through the End of 2026?
Four calls for the final quarter of the year, ranked by our confidence in them.
AI Content Keeps Mainstreaming
AI-Generated reaching the global top 10 is not a ceiling; it’s a checkpoint. The growth engine has shifted — the first wave was driven by novelty and image generation, the current wave by interactive companion experiences and dramatically better video models — and the open questions for Q4 are regulatory, not technical. Consent frameworks and platform policies are now the main variables shaping where this category tops out.
VR’s Strongest Quarter Begins Now
VR share is up in all six regions, hardware prices keep falling, and the indoor season now beginning is historically VR’s strongest stretch of the year. A 70–80% full-year consumption gain is our conservative case; doubling is plausible. The wildcard is passthrough AR, which early industry coverage suggests could become VR’s next format leap in 2027.
The Roulette Cluster Stays Hot
With searches up 38% this month alone and a brand-style term in the global top 10, we expect the random chat cluster — successor platforms, archive clips, and hybrid cam-roulette formats — to remain a top-10 riser through year-end. The adjacent live cam space benefits from the same appetite for real-time interaction; our ranking of the best live sex cam sites maps that territory.
Authenticity Keeps Grinding Forward
Real Couples up, Casting and Massage down, performer-name searches taking share from category searches: it’s all one trend wearing different labels. The direction of travel is unmistakable — toward specific people, real dynamics, and interactive formats, and away from anonymous studio output. This is the slowest force in the report and the one we’d bet on furthest into the future.
FAQ
What is the most popular porn category in September 2026?
Lesbian holds the #1 spot by global search volume, as it has in nearly every public ranking for years, with MILF close behind at 95 on our 100-point index. The top 5 — Lesbian, MILF, Japanese, Hentai, Amateur — is stable; the movement is all in the middle of the table.
Why is AI porn growing so fast?
Two engines. Generation quality crossed a believability threshold for images and, increasingly, video. And interactive companion experiences — persistent AI characters you chat with rather than clips you watch — imported a habit from mainstream companion apps, one of 2026’s fastest-growing consumer AI segments. The +52% monthly rise in companion content is the sharpest single-month gain in our data this year.
What is the back-to-school effect?
A seasonal pattern, documented for years in Pornhub Insights reports, in which college-related searches spike every September and early October as the academic year begins. Our estimate puts this year’s College surge at +44% month-over-month. It fades by November, every year, like clockwork.
Is VR porn actually growing, or is it hype?
Growing, and measurably: VR share of viewing is up in all six regions we track, led by Europe at 13%. Falling headset prices are the main driver, and the autumn indoor season is historically VR’s strongest quarter. Juniper Research projected global adult VR revenue reaching $19 billion by 2026, and the consumption data is broadly consistent with that trajectory.
How reliable are these numbers?
Treat them as well-informed estimates, not measurements. The index scores and percentage changes are our own editorial modeling built on public sources — Pornhub Insights annual statistics, Google Trends search data, and SimilarWeb traffic analytics. They are good at describing relative movement (what’s rising against what’s falling) and not intended as absolute traffic figures. No one outside the platforms themselves has the raw numbers.
The Verdict
If you only take four things from this first report, take these: the top categories are stable and will stay that way; AI has gone from curiosity to top-10 category and its interactive form is the fastest-growing thing we track; September’s traffic rebound and College surge are the calendar doing what the calendar always does; and the deep current under everything — the one that explains both the risers and the decliners — is the pull toward authenticity and interaction over anonymous studio output.
We’ll run these numbers again and report back as the trends develop — the winter peak, the October cosplay spike, and the question of whether AI’s climb continues are all on the watchlist. Consider this the baseline.
Methodology note: category scores are indexed to 100 against the top category’s search volume. Percentage changes are month-over-month editorial estimates modeled on Pornhub Insights annual statistics, Google Trends search data, and SimilarWeb traffic analytics. Regional figures reflect relative search share within each region, not absolute volume.
More from the Blog